After the interim report, there was a divergence in the stock price trends of Meixue Group (02097.HK, hereinafter referred to as "Meixue") and Guming (01364. HK). As of the close on September 2, Meixue's stock price fell 16.17% from the interim report, while Guming's stock price rose slightly by 0.95%. The gap in market value between the two new tea beverage companies has further narrowed, with Meixue's market value of HKD 79.1 billion and Guming's market value of HKD 59.5 billion.
Bright Company has previously conducted a comparative analysis of the financial figures of Meixue Bingcheng, Guming, and Luckin Coffee. Intuitively, the decline in Meixue's stock price is due to its lower than expected revenue, profit, and same store GMV growth rate. Among them, Meixue's net profit attributable to the parent company in the first half of the year decreased by 14.7% year-on-year, and the brokerage calculated that Meixue's single store revenue declined by about 17%.
And Gu Ming's financial report figures are considered to be beyond expectations. In addition to the above main indicators, the performance of Guming in the same store is more worthy of attention. According to financial reports, the daily GMV of Guming's single store is 7800 yuan, a year-on-year increase of 2.6%; The daily average cup volume of a single store is 440 cups, which is basically the same; The unit price of the cup is 17.8 yuan, a year-on-year increase of 3.1%.
One reason for the changes at the store level is the changes brought about by the "second curve" of Guming Coffee. The company's CFO Meng Hailing said at the performance meeting, "Without coffee and early morning hours, it would be difficult for us to maintain growth in the first half of the year." According to the disclosed figures, as of the end of June, about 13500 stores of Guming had been equipped with coffee machines, covering 94% of the stores.
Gu Ming also gave a number at the performance meeting, stating that the company's non promotional coffee accounted for over 20% of stable store sales and over 25% during promotional periods. According to a research report by CICC, the current cup volume of coffee in Guming accounts for about 20%. The above numbers fully reflect the changes brought by the second curve to the company's growth and profits.
Mi Xue and Gu Ming adopted different strategies when working on the 'second curve' together. Mixue is building an independent coffee brand called "Lucky Coffee", while Guming is expanding the coffee SKU categories in existing stores. At present, Gu Ming's route seems to be more effective, and Mi Xue seems to have realized that it has chosen to increase the coffee category in the stores of the main brand "Mi Xue Ice City". However, the coverage rate of the main brand coffee machines is still in a relatively low range (about 7%).
Similarly, Luckin Coffee (LKNCY. US) has also chosen to sell tea beverage products (light milk tea) in coffee shops, achieving good results. CHA. US, on the other hand, had previously attempted an independent brand called "Cha Ji Xian Cui", but ultimately failed.
From this perspective, it seems that "adding new categories" is easier to succeed than "becoming a second brand" at present. Relying on opening new stores to boost growth has actually encountered industry bottlenecks, and there is still room for improving same store performance.
It is also a story of growth, but the market has given different feedback on how to tell this story.
Cost differences reflect efficiency
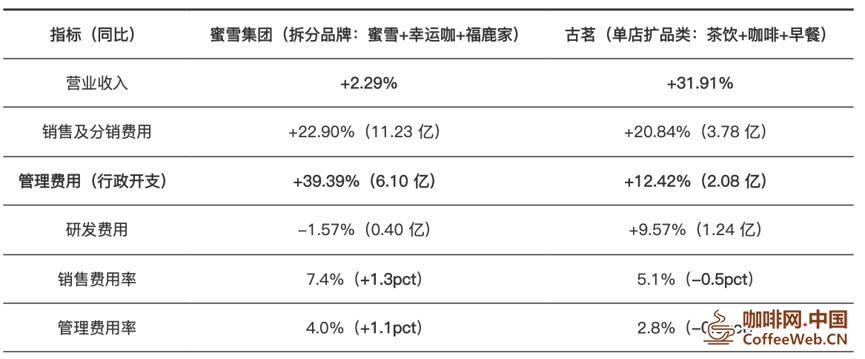
To understand the difference between Meixue and Guming on the "second curve", one must first look at the cost structure. Mixue's expense growth rate is significantly higher than its revenue growth rate, while Guming is the opposite.
Source: Financial report, compiled by AlphaEngine
In the first half of 2026, Meixue's revenue increased by 2.29% year-on-year, but sales and distribution expenses increased by 22.90% year-on-year, reaching 1.123 billion yuan; Administrative expenses increased by 39.39% year-on-year, reaching 610 million yuan; Research and development expenses decreased by 1.57% year-on-year to 40 million yuan. In terms of corresponding expense ratio, the sales expense ratio is 7.4%, an increase of 1.3 percentage points year-on-year; The management expense ratio is 4.0%, an increase of 1.1 percentage points year-on-year.
This means that despite low single digit income growth, sales and management expenses are still increasing for Mixue. The cost growth rate is significantly higher than the income growth rate.
Gu Ming's direction is opposite. In the first half of 2026, Guming's revenue increased by 31.91% year-on-year, and sales and distribution expenses increased by 20.84% year-on-year, reaching 378 million yuan; Management expenses increased by 12.42% year-on-year to 208 million yuan; The research and development expenses increased by 9.57% year-on-year to 124 million yuan. The sales expense ratio was 5.1%, a year-on-year decrease of about 0.5 percentage points; The management expense ratio is 2.8%, a year-on-year decrease of about 0.5 percentage points.
That is to say, the income growth rate of Guming is higher than the expense growth rate, and the expense ratio is decreasing. Honey Snow's income growth rate is lower than the expense growth rate, and the expense ratio is increasing.
Bright Company believes that this is related to the coffee making paths of the two companies.
Meixue's' Lucky Coffee 'requires an independent brand, independent store network, franchise management system, product system, and marketing investment. Even if the supply chain can reuse the Meixue system, brand operation and franchise management will still incur organizational costs.
In addition, Meixue is also promoting the "True Fresh Pure" three-year plan, including short-term guarantee of raw materials, cold chain and three temperature distribution, intergenerational upgrading of the supply chain, and expansion of production bases. These investments are related to the upgrading of the main brand, as well as new categories such as coffee, fresh milk, and cold chain juice.
Guming is not rebuilding a coffee brand, but adding coffee categories to existing stores. Its cost curve is closer to "reuse" – the same set of stores, the same batch of franchisees, the same supervision system, and the same warehousing logistics can serve more SKUs.
From the perspective of capital expenditure, franchisees also face much less pressure. According to market related information, the equipment for Guming Coffee is mainly borne by franchisees and adopts a phased approach. Market data also shows that a fully automatic coffee machine from Guming costs about 70000 to 100000 yuan (Shelley or Eversys), and franchisees can also pay in installments by paying a deposit of about 15000 yuan and returning it in installments. For franchisees, this is not about opening a new store, but adding a device to an old store, and this device can also be recycled or circulated in the market as a second-hand item.
The difference brought about by this is very direct – the marginal rent of coffee adding equipment is almost zero, the addition of new labor is limited, and the store's existing water and electricity, warehousing, employees, and online channels can all be reused. But opening a lucky coffee shop alone, franchisees have to bear the full investment of the store.
This may explain why the market responds differently to the valuation of the two paths.
Moreover, coffee products further balance the consumption of Guming at different times, especially in the breakfast scene, which increases the efficiency of the store.
During the store expansion period, independent brands can bring new store numbers, new GMV, and greater imagination space. But in the stage of single store pressure and tight cash flow for franchisees, independent brands will also amplify operational costs and capital expenditure pressure.
Second curve: Meixue relies on new stores, Guming relies on same store
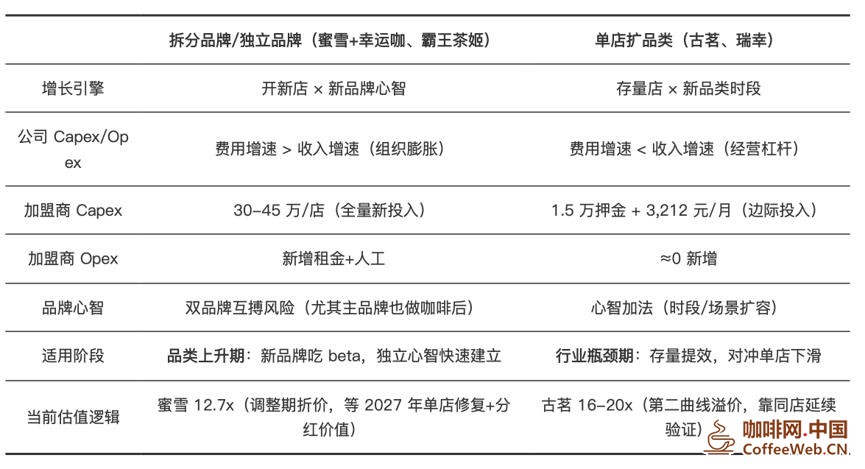
The difference between Gu Ming and Mi Xue (source: AlphaEngine)
Mixue and Guming both consider coffee as the second curve, but their growth patterns are different.
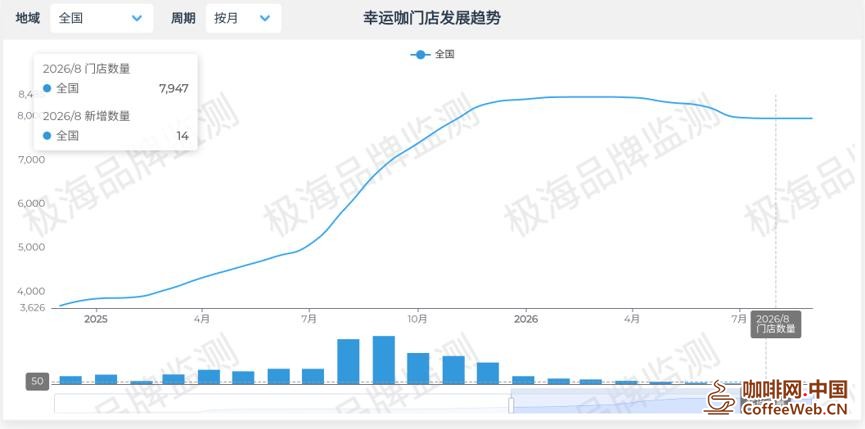
Mixue's coffee growth mainly comes from new store openings and independent brand expansion. There is no official disclosure of the revenue and profit of Lucky Coffee on the market, but according to data from Jihai, there are currently about 7900-8000 Lucky Coffee stores. Since the beginning of this year, the number of new Lucky Coffee stores has significantly slowed down, with only 14 new stores added in August, compared to 892 new stores added in August last year.
Source: Monitoring data of Jihai brand
At the same time, the main brand of Meixuebing City is also laying freshly ground coffee, which will also cause the problem of "diversion".
The price bands of the two are close, with a high degree of overlap in customer groups, and the points are also concentrated in the sinking market. The main products of Lucky Coffee are priced at around 5 to 10 yuan, and the main brand of freshly ground coffee, Honey Snow, is also in the low price range.
For franchisees, this issue is even more important. Opening a lucky coffee shop requires a full investment, while adding coffee to the Meixue Ice City store requires even lower investment. If two brands cover the same customer base, franchisees will recalculate the return period. This will affect the speed of opening Lucky Coffee stores and also affect the expected increase in the second curve of Honey Snow Coffee.
Mixue seems to have realized this issue. At the performance meeting, the company's management proposed that in 2026, the company will focus on improving the quality of store operations, continuously investing in infrastructure and operational systems, while steadily and prudently expanding store scale
Let's take a look at Gu Ming again.
As mentioned earlier, as of the first half of 2026, approximately 13500 stores of Guming will be equipped with coffee machines, with a coverage rate of about 94%. At present, the proportion of Guming's coffee in store sales has remained stable at over 20%, with over 25% during the promotional period. China International Capital Corporation predicts that the current coffee cup volume of Guming accounts for about 20%. The management's goal is to maintain a stable coffee proportion of 25% to 30% by the end of 2026 to the first half of 2027. Currently, over 50% of the customers who purchase Guming Coffee are new customers, and the price per cup is about 10 yuan, which is similar to some products from Luckin Coffee. Coffee not only brings new customers, but also supplements early morning consumption.
Franchise profits have also become a market focus after the financial report.
The management of Guming conducted a monthly breakdown of franchisee profits at the performance meeting, and in the first quarter, franchisee profits exceeded the same period last year; May is under pressure, mainly due to weather conditions, a high base of takeaway orders from last year, and a high proportion of takeaway orders; Sales data and franchisee profits have significantly improved from June to August.
Moreover, Guming's net increase in stores in the first half of the year was only 797, lower than the 1265 stores in the same period last year, and also lower than the market's linear expectation for opening stores throughout the year. The company stated that slowing down the opening of stores is proactive control, and the opening of poor quality stores will dilute the business of existing franchisees, ultimately damaging the franchise ecosystem.
Gu Ming's logic is that, in a situation where the number of stores is close to saturation, instead of allowing franchisees to continue opening stores through new brands, the same store can gain more time slots and more categories, thereby achieving better profitability. Coffee and morning business hours serve this goal.
This may also be one of the reasons why the stock price of Guming rose after the mid year report. What the market sees is not simply a coffee "second curve" story, but rather a reflection of coffee's GMV, cup price, franchisee profit, and company profit margin at the individual store level.
The Beta of opening a new store has disappeared, and a single store needs to create an Alpha
In the upward trend of the industry, independent brands are a easier way to tell growth stories. A new brand means a new network of stores, new market space, and a new revenue curve. In the past, Meixue was able to incubate lucky coffee by relying on a low-priced supply chain, a network of franchisees, and coverage in lower tier markets. This set of abilities is valid during the store opening bonus period.
But by 2026, the industry will enter another stage.
The density of tea beverage stores has increased, and there is competition from brands such as Luckin Coffee, Kudi Coffee, Lucky Coffee, and Kenyue in the coffee market. The low-end market is also constantly being developed. After the subsidy for food delivery was reduced, the revenue of individual stores began to come under pressure. At this point, franchisees are more concerned about individual store profits.
In this environment, independent brands will face two constraints: first, the quality of newly opened stores will decline (such as due to the impact of location), and second, the return cycle of franchisees' funds will become longer. If the main brand and the new brand have overlapping price bands, locations, and customer groups, the willingness to open a store will be further affected.
The institutional perspective also reflects this difference. JPM evaluated the interim report of Guming as "exceeding expectations", stating that the adjusted core profit exceeded its estimate by 15% and exceeded the buyer's consensus by 8%.
This also explains the change in market value pricing narrative: in the past, the market looked at store growth rate, but now the market looks at single store output. Or, in the past, the growth of store numbers was a larger Beta, but after the industry's Beta disappeared, it is now necessary for stores and brands to create their own Alpha.
At least for now, Guming's route is more recognized by the market.
This article is from WeChat official account "Suchbright" (ID: suchbright). The author: editor in chief is online 24 hours a day. 36 krypton is authorized to release.