
When we talk about Chinese coffee, we are really talking about more than a drink — it is a complete industry chain from land to consumption. On this chain, the frenzy of the consumer market and the breakthrough at the origin are happening on the same timeline: at one end, coffee shops opening ever denser in cities; at the other, the increasingly precious coffee gardens on the slopes of southern Yunnan.
I. Market frenzy: a track racing toward ¥350 billion
The explosion of China’s coffee consumption is not an overnight story, but an upward curve precisely recorded by data. According to the “2024 China Urban Coffee Development Report” (jointly released by Hongqiao International Coffee Port and others), China’s coffee industry reached ¥265.4 billion in 2023, was projected to rise to ¥313.3 billion in 2024, and by 2025 this figure would climb to ¥354.9 billion, up about 13.3% year on year. The three-year compound annual growth rate (CAGR) held steady at 17.14% — a curve that stands out against the backdrop of slowing overall consumption growth.
Supporting this curve is the real consumption in the cup. In 2023, China’s per-capita annual coffee consumption was about 16.74 cups; by 2025 it was projected to rise to 28.57 cups, over 70% growth in three years. A horizontal comparison shows the room more clearly: US per-capita annual consumption is over 300 cups, Japan about 200, while China is still in a low range — meaning long-term growth is far from topping out. Coffee is sinking from a “niche ritual” in first-tier cities into a “daily habit” for a broader population; the structural expansion of the consumer base deserves more attention than the total-volume growth.
In consumption form, the rise of freshly brewed coffee is especially key. In 2023, the freshly brewed market was about ¥162.35 billion, 40.2% of the whole industry; by 2025 it was projected to exceed ¥188 billion, further dominating. The land-grab by chain brands is an intuitive footnote: taking Shanghai as an example, the city has 9,553 coffee stores, about 6.1% of the national total, with Starbucks and Luckin taking about 18% and 14% market share respectively. When a milk-tea shop inevitably has a coffee shop next door, “coffee density” has become a new indicator of urban commercial vitality, also reflecting capital and supply chains’ collective bet on this track.
More intriguing is the fission of consumption scenarios: from the “third place” for business talks, to the “grab-and-go” on the commute, to the “lifeline” daily essential in the office, coffee is being broken into multiple functional labels. Meanwhile, RTD coffee, liquid coffee and freeze-dried powder are rapidly penetrating supermarkets and e-commerce, letting coffee consumption break the store radius and enter homes and journeys. The more fragmented the scenarios, the larger the market — this is the internal logic of the industry’s continued rise.
On the other side of growth is the sinking of the market. As coffee penetration in first-tier cities saturates, chain brands and independent cafés are accelerating their extension to third- and fourth-tier cities and even counties. Lower rent and labor costs, combined with the return of young populations, make lower-tier markets one of the fastest-growing segments. The price of a cup of coffee is shifting from “light luxury” in first-tier cities to “daily” for small-town youth; this process of consumption democratization is the social foundation for the industry’s continued expansion.
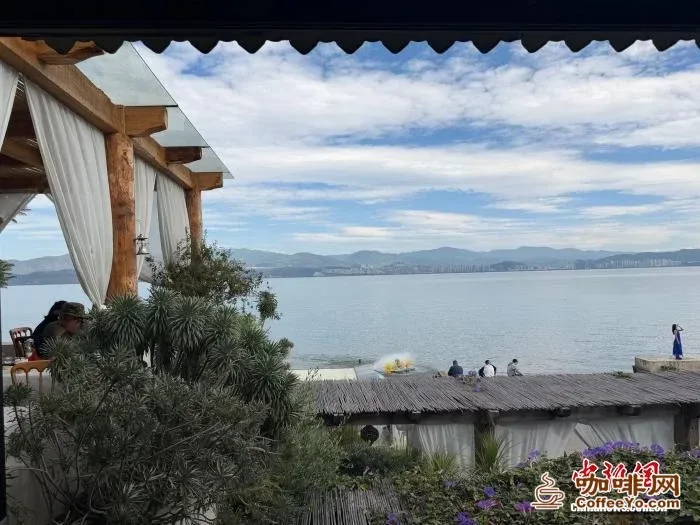
II. Yunnan’s breakthrough: from “minus 30 cents” to “plus 5 cents”
The center of gravity of the industry chain is migrating toward the source. China’s coffee map almost coincides with Yunnan — in 2023, Yunnan’s coffee planting area was 1.146 million mu with output of 146,000 tonnes, both over 98% of the national total. Among these, Pu’er alone contributed about 55% of output, Lincang and Baoshan about 15% each, forming a planting cluster centered on southern Yunnan, with extremely high geographical concentration — also providing natural origin boundaries for standardization and branding.
A deeper change is happening at the value level. In 2021, Yunnan’s coffee specialty rate was only 8% and deep-processing rate about 20%; by 2023, the specialty rate jumped to 22.7% and the deep-processing rate rose to 56%. The specialty rate measures the proportion of beans entering the specialty supply chain with recognizable flavor; the deep-processing rate measures the proportion completing value-added steps like roasting and extraction locally. The simultaneous rise of both figures means Yunnan is turning from “selling green-bean raw material” to “selling flavor and brand,” and the value-added of the industry chain is beginning to flow back locally from overseas.
The most dramatic footnote comes from the procurement side. Starbucks has purchased over 65,000 tonnes of Yunnan green beans in the past 12 years, with its acceptance pass rate rising from 20% early on to 80%; and more crucially, the reversal of pricing power — in early years Yunnan beans were often pressed by international buyers at “minus 30 cents/lb,” but now quality beans can negotiate “plus 5 cents/lb.” The gap of more than 30 cents measures the distance of an industry chain moving from passive to active, and is also a microcosm of Chinese coffee’s rising position in the international value chain. It shows one thing: when quality is solid and standards are clear, the source is no longer just a price taker.
Supporting this turnaround are the upgrading of processing methods and the progress of estate management. From traditional washing to natural and honey processing, from crude picking to graded harvesting, Yunnan coffee is using more refined agronomy to exchange for more stable cupping performance. More and more coffee estates are building their own flavor profiles and traceability systems, writing “which mountain, which plot, what processing” into the identity of every bag of beans — precisely the prerequisite for specialty status to hold.
III. Value-chain restructuring: specialty, deep processing and digitalization
Raising the specialty rate is only the starting point. When the deep-processing rate rose from 20% to 56%, it means over half of Yunnan beans no longer leave the province as primary raw material, but complete value-added steps such as roasting, extraction and freeze-drying locally. This not only retains output value, but also keeps employment and tax revenue, upgrading the producing area from a “raw-material base” to a “manufacturing node.” One more process a bean walks locally, one more share of value the producing area keeps.
The product forms of deep processing are also enriching: cold-brew concentrate, drip bags, coffee freeze-dried powder, RTD cans — these high-value-added forms extend shelf life and reduce logistics loss, and also let Yunnan coffee break free from the limitation of “only freshly brewed,” entering a broader sales network. For the producing area, this is the key leap from “selling agricultural products” to “selling consumer products.”
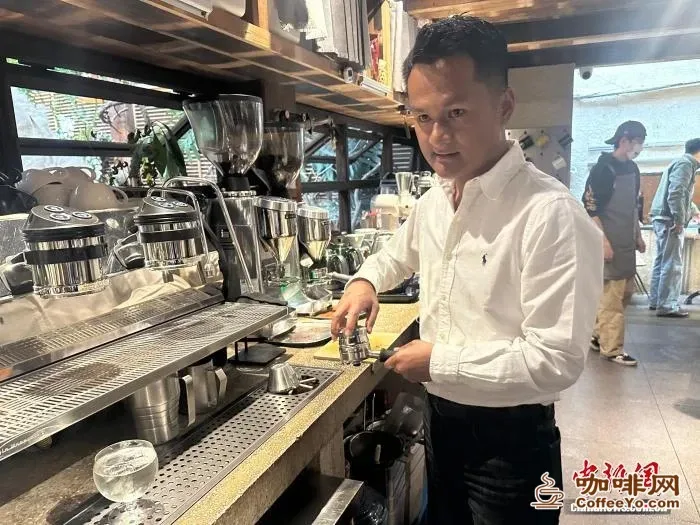
People are the most active yet scarcest element on the value chain. As the chain lengthens, demand for baristas, roasters, cup tasters and producing-area brand operators is rapidly expanding. Local Yunnan vocational colleges and leading enterprises are jointly building industry-education-integrated coffee talent systems, connecting the two abilities of “knowing how to grow beans” and “knowing how to sell beans.” When behind a cup of coffee stand not only farmers but a whole professionalized career chain, the upgrading of the producing area truly has people to sustain it.
Digitalization provides the infrastructure for this restructuring. The official launch of the coffee digital-trading infrastructure moves green-bean trading from “sample inspection and negotiation” toward “standard pricing, online matching, traceable verification.” For producing areas long dependent on verbal contracts and scattered procurement, a standardized trading foundation is the prerequisite for branding and financialization, and the bridge for small and medium estates to connect with the big market. When trading is transparent and traceability trustworthy, financial capital dares to enter, and insurance and credit can catch the risk.
From one bean to one good cup of coffee, Yunnan is trying to translate “geographical indication” into “quality language”: altitude, flavor wheel, processing method and estate story gradually become signals recognizable by consumers. When coffee-shop menus begin to show origin labels like “Yunnan Natural” and “Yunnan Honey,” the realization of source value truly begins — terroir is no longer just origin endorsement, but a product attribute that can be priced and repurchased.
IV. Hidden worries and challenges
Beneath the halo, challenges are equally real. In 2023 Yunnan’s coffee export was 9,857 tonnes, down about 68% year on year — this sharp fluctuation was affected both by international demand and logistics disruptions, and reflects the old problems of external dependency and passive pricing. As domestic consumption becomes the main engine, how to balance domestic sales and exports, and how to protect growers’ income amid international price swings, are unavoidable topics. The export plunge reminds us: betting all hope on external markets leaves too large a risk exposure.
Moreover, brand premium remains thin. Despite the rising specialty rate, the recognition and premium power of “Yunnan beans” in the terminal market are still hard to match the century-old brands of traditional origins like Colombia and Ethiopia. The spread speed of standardization, traceability and sustainability certifications (such as Rainforest Alliance, organic) will determine whether Yunnan coffee can truly move from “large volume” to “high price,” from “being procured” to “being specified by name.” A brand is not built in a day; it requires consistent quality and storytelling ability.
There is also an invisible threshold of talent and cognition. Cup tasters, roasters, producing-area brand operators — these key roles connecting source and consumer remain scarce resources in Yunnan. Without enough people to translate “good beans” into “good products,” the results of specialization easily stay at the raw-material level and are hard to convert into terminal premium. For the industry chain to truly lengthen, the talent chain must lengthen first.
Cost-side pressure is also unavoidable. Rising prices of agricultural inputs, labor and logistics are compressing the profit space at the planting end; while terminal brands battle over price subsidies, the good beans upstream may not fetch a good price. How to transmit the prosperity at the consumer end more evenly into farmers’ pockets is the touchstone of the industry’s healthy development — only when the source is profitable can quality improvement be sustainable, and the industry’s roots grow deeper.
V. Outlook: the next decade
Standing at the node of Chinese coffee’s golden decade, trends have taken shape: the consumption end keeps expanding, the supply end accelerates specialization and deep processing, and the trading end moves toward digitalization and standardization. Yunnan’s role will upgrade from “China’s coffee raw-material library” to “the value source of Asian specialty coffee” — not only a geographical migration of industry, but a restructuring of value distribution.
Several main threads can be foreseen: first, consumption stratification will deepen further, with both the affordable-requisite and high-end-specialty ends growing simultaneously; second, producing-area branding will refine from the provincial concept of “Yunnan” to municipal and even estate-level labels such as “Pu’er,” “Baoshan” and “Lincang”; third, sustainability and carbon neutrality will become hard thresholds for exporting to Europe and America, forcing green transformation at the planting end; fourth, coffee tourism and origin experiences will extend consumption scenarios back to the fields, forming a closed loop of “drink coffee — understand coffee — go to the origin.”
Internationalization will also rewrite Yunnan coffee’s narrative. In the past Yunnan beans were mostly exported as raw material; now, with rising specialty rate and brand power, “Made in Yunnan” is beginning to go overseas to specialty channels as finished products, with brands and flavor stories. Domestically, it supplies the upgrading of domestic consumption; abroad, it is a sample of Chinese agricultural products’ value chain climbing upstream. Under two-way flow, Yunnan coffee’s role is shifting from “purchased by the world” to “telling the world its own terroir.”
There is no shortcut on this road. It requires growers to hold the cupping quality, brands to tell the terroir story well, and capital and policy to patiently accompany the run. But what is certain is — as 1.4 billion people’s coffee cups gradually fill with “Chinese flavor,” this industry breakthrough about one bean has only just begun, and its answer is being written in every coffee garden of southern Yunnan.
Sources
(Note: All data in this article are cited from publicly verifiable sources, subject to the original texts.)
· “2024 China Urban Coffee Development Report” (jointly released by Hongqiao International Coffee Port and others)
· Public data from the Yunnan Provincial Department of Agriculture and Rural Affairs (2023 coffee planting area, output, specialty rate, deep-processing rate)
· Public disclosure of Starbucks’ Yunnan coffee procurement
· Public reports from the National Bureau of Statistics and industry research institutions
Original Work Statement
- This article is an original work of coffeeyo.com. Without authorization, no media, website or individual may reprint, extract, reproduce or otherwise use it; violators will be held legally responsible.
- All images, charts and videos herein are originally shot or produced by coffeeyo.com and carry copyright watermarks; copyright belongs to coffeeyo.com.
- For reprint authorization, commissioned writing, interviews or business cooperation, contact: Tel 400-0000-641 (+86-18288016826) | Email 405854472@qq.com | Address: Jinghong City, Xishuangbanna, Yunnan Province / Tieling City, Liaoning Province
Related Reading
 Three Decades of Shanghai-Yunnan Collaboration: A Coffee Bean ‘Ferments’ at the Import Expo
 Why Yongde’s Coffee Beans Won Gold in Shanghai – A Taste of ‘Life in Yunnan: 365 Days’
- Yunling Commentary: Yunnan Coffee Turnaround Hinges on Autonomous Pricing
 A ‘Travel Pack’ Reveals Another Possibility for Pu’er Baristas
- Bean in Short Supply: A Taiwan Youth on Yunnan Coffee as a Shared Cross-Strait Stage
- Five Years, Eight Championships: Lincang Coffee Joins the World Stage


 Liaoning ICP Security No. 21122402000217