On the evening of August 26th, Gu Ming (HK1364) released its performance announcement for the first half of 2026, delivering a report of both increased revenue and adjusted profit. At the same time, Guming (HK1364) is actively slowing down its store opening pace, with new categories such as coffee and breakfast becoming the new pivot for this Wandian tea beverage to support its single store growth.
Revenue and profit both increased, and Guming's operational efficiency steadily improved in the first half of the year
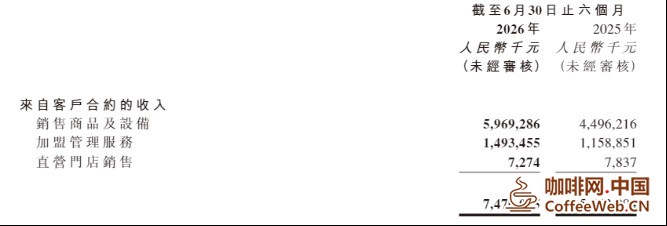
According to the financial report, in the first half of 2026, Guming (HK1364) achieved a revenue of 7.47 billion yuan, a year-on-year increase of 31.9%; Adjusted profit (not measured by International Financial Reporting Standards) was 1.57 billion yuan, a year-on-year increase of 44.4%; The gross profit margin also increased from 31.5% in the same period of 2025 to 33.4%, a year-on-year increase of 1.9 percentage points.
From the perspective of income composition, sales of goods and equipment account for nearly 80%. In the first half of 2026, Guming (HK1364)'s sales revenue from goods and equipment reached 5.969 billion yuan, a year-on-year increase of 32.8%, accounting for 79.9% of the total revenue; The revenue from franchise management services was 1.493 billion yuan, a year-on-year increase of 28.9%, accounting for 20.0% of the total revenue; The revenue of directly operated stores was 7.274 million yuan, a slight decrease of 7.2% year-on-year.
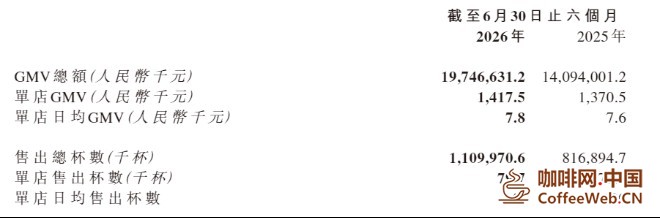
In terms of store performance, in the first half of 2026, the total GMV of Guming (HK1364) reached 19.747 billion yuan, a year-on-year increase of 40.1%. The daily GMV of a single store has increased from 7600 yuan in the same period last year to 7800 yuan; The daily average number of cups sold in a single store increased by 1 cup, from 439 cups to 440 cups; From this perspective, the increase in GMV comes more from the contribution of newly opened stores and the increase in average customer value. According to calculations, the average customer value per store of Guming (HK1364) increased from about 17.3 yuan to about 17.7 yuan in the first half of this year.
In terms of membership size, as of the end of the reporting period, the number of registered members on the Gu Ming (HK1364) mini program has exceeded 236 million, with approximately 59 million quarterly active members.
Slow down opening stores, parallel deepening of low line cultivation and breakthrough of high line
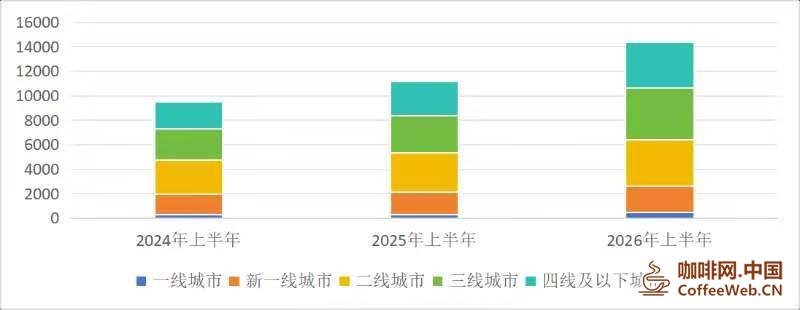
As of June 30, 2026, the total number of Gu Ming (HK1364) stores reached 14351. During the period, 1318 new stores were opened, a decrease of 252 from 1570 in the same period last year, a year-on-year decrease of 16.1%; 521 stores were closed, an increase of 216 stores compared to the same period last year, a year-on-year increase of 70.8%.
The company stated that the slowdown in new store growth is mainly due to the company's increasing focus on store quality, prioritizing the upgrading of existing stores to sixth generation stores, and implementing stricter site selection standards for new stores; The increase in the number of closed stores is mainly due to a high initial store base.
From the perspective of urban line level distribution, Guming (HK1364) continues to consolidate its advantages in the lower tier market and actively layout in higher tier cities.
As of June 30, 2026, second tier and below cities are still the basic market, with a total of 11739 stores, accounting for 82%. Among them, there are 3811 second tier cities, a year-on-year increase of 18.8%; The number of third tier cities reached 4208, a year-on-year increase of 37.4%; There are 3720 cities in the fourth tier and below, a year-on-year increase of 33.9%.
From the net increase in the number of stores in the first half of 2026, there is a clear differentiation among various tier cities. First tier cities saw a net increase of 43, an increase of 7 compared to the 36 in the first half of 2025, making it the only market with a year-on-year expansion in net increase; The net increase of new first tier cities decreased from 131 in the same period last year to 74; The number of second tier cities has significantly decreased from 347 to 70; The number of third tier cities has decreased from 395 to 323; The number of cities in the fourth tier and below has decreased from 356 to 287.
It is worth noting that although the growth rate of the number of stores in first tier cities leads all tier cities, with a year-on-year increase of 44.3%, the volume is relatively small, only 459, accounting for 3.2% of the total number of stores.
Furthermore, in terms of regional distribution, Guming (HK1364) stores are mainly concentrated in the East, Central, and South China regions. Red Food Big Data shows that in its "headquarters" in Zhejiang Province, Guming (HK1364) has over 2600 stores, nearly 2000 stores in Guangdong, and over 1000 stores in Fujian and Jiangxi. Its core advantage areas are stable. While deeply cultivating advantageous regions, Guming (HK1364) is also orderly promoting nationwide layout. According to public reports, Guming (HK1364) announced plans to open about 4000 new stores by 2026, accelerating store expansion in non dominant regions such as Yunnan, Guizhou, Sichuan, Chongqing, Hebei, and Shandong, while continuously optimizing locations and increasing layout in advantageous regions.
Regarding Gu Ming (HK1364)'s differentiated store expansion strategy of deep cultivation in second tier and lower tier cities with high regional concentration, Zhang Yi, CEO and Chief Analyst of iMedia Consulting, analyzed in an interview with Dahe Caili reporters that the lower costs of labor and other aspects in lower tier cities are helpful for the rapid expansion of stores; If the store operation is stable, a dense network of stores can still build high barriers within the region.
However, it should be noted that the consumption capacity of the low-end market itself (883434) is limited, and the market expansion space is easily reaching the ceiling, "said Zhang Yi. In addition, in the current environment of intensified industry competition, there may be difficulties for Guming (HK1364) to break through to the high-end and northern markets, such as high costs in high-end cities, which will squeeze the profits of the cost-effectiveness model; The mindset of local high-end tea beverage brands takes priority. Cross regional expansion, especially entering the northern market, requires overcoming two hurdles: the completeness of supply chain infrastructure and the seasonality of consumption (883434).
Coffee machines are installed in 90% of stores, and it's not milk tea that supports single store growth
In the first half of this year, Guming (HK1364) had intensive actions on the product side: promoting coffee, selling breakfast, and even trying bottled drinks.
In the performance announcement, there is a set of data: as of June 30, 2026, for the six months ended, Guming (HK1364) has launched 51 new products. It is worth noting that 12 of them are new coffee drinks, accounting for 23.5% of the new products. In addition, as of June 30th, about 13500 Guming (HK1364) stores have been equipped with coffee machines, with a coverage rate of about 94%.
In addition, in the first half of the year, Guming (HK1364) further expanded its consumption (883434) scene, with some stores launching breakfast baking lines and some stores selling beef rolls, sandwiches, egg tarts and other products in Hangzhou and other regions.
The coffee+breakfast business line has brought considerable revenue to Guming (HK1364). The announcement shows that in the first half of this year, the GMV per store, average daily GMV per store, number of cups sold per store, and average daily number of cups sold per store of Guming (HK1364) remained relatively stable compared to the same period last year, mainly due to the diversification of coffee beverage types and the expansion to breakfast scenes.
The product line of Guming (HK1364) has even gone out of stores and onto supermarket shelves. In June of this year, Guming (HK1364) HPP bottled juice entered retail channels such as supermarkets, snack shops, and convenience stores.
When it comes to the multi category extension of Wandian tea beverage brand, Zhang Yi believes that its core value lies in seizing more consumption periods (883434), spreading fixed costs and supply chain costs more thinly, and "more importantly, improving operational indicators such as floor area efficiency and average customer price".
At present, Guming (HK1364) has made significant breakthroughs in its coffee category. Its previously launched products such as Kuji Ganlai Latte have become popular on social media. Guming (HK1364) has also proposed the "30 day fresh bean" standard to enhance the coffee consumption experience (883434).
It may not be easy for new tea beverage brands to cross over and make coffee, "said Zhang Yi. Professional brands such as Luckin Coffee, Kudi Coffee, and Lucky Coffee have advantages in supply chain efficiency, price, and brand awareness. If tea beverage brands compete with traditional coffee brands, they may not necessarily have stronger competitiveness. In his opinion, innovative categories such as tea and coffee are the opportunities for tea beverage brands, and the key still lies in product innovation.
Editor in Chief: Li Wenyu | Reviewer: Chen Xiaojuan | Reviewer: Li Zhen | Supervisor: Guzheng
 Liaoning ICP Security No. 21122402000217