
Brief (coffeeyo.com): An americano at 8 a.m., an iced coffee after lunch, another round with colleagues mid-afternoon — coffee in China is quietly ceasing to be an occasion and becoming a reflex. With 660 new coffee launches in six months and 284,000 outlets nationwide, the cup increasingly resembles an everyday commodity.
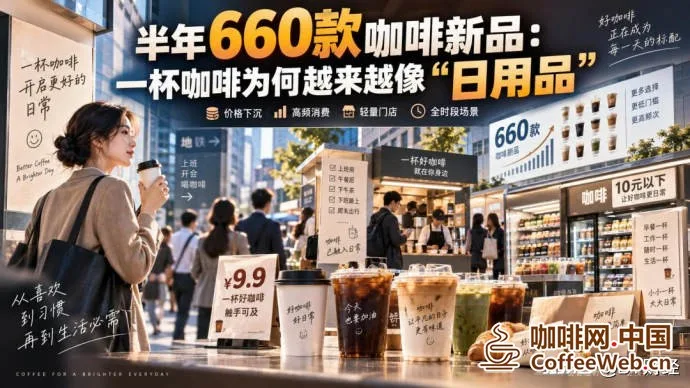
An americano bought below the office tower at 8 a.m.; an iced coffee tapped out almost without thinking after lunch; a delivery order shared with colleagues when the mid-afternoon slump hits.
Something interesting is happening to the way Chinese people consume coffee.
Many no longer set out specifically “to go for a coffee”.
They simply pick one up along the way.
That shift may matter more than how many new cafés have opened.
According to the 2026 Coffee Beverage Category Development Report, 117 made-to-order beverage brands launched no fewer than 660 new coffee products in the first half of 2026. By June, the country had 284,000 coffee outlets, up 20.1% year on year. Over the same half-year, average spend per visit at coffee outlets held steady at around RMB 25, while new coffee products priced below RMB 10 rose to 11.7% of the total.
Another set of figures makes the point even more plainly: annual per-capita coffee consumption in China climbed from 16.7 cups in 2023 to 28.6 cups in 2025.
Nearly 12 extra cups in two years.
Put those numbers together and it becomes clear that China’s coffee market is crossing an important threshold:
coffee is turning from a “lifestyle product” that demanded a deliberate purchasing decision into an everyday consumer good — more frequent, more convenient, and ever lower in the thought it takes to buy.
That also means the way the coffee industry makes money is changing.
Where the competition once revolved around brand, store ambience and how much a single cup could fetch, it is increasingly about a different set of variables:
price band x purchase frequency x utilisation of dayparts x single-store efficiency.
660 launches in six months: why does coffee need so many new products?
What does 660 launches in half a year actually mean?
On average, those 117 sample brands brought out more than three new coffee products every single day.
More tellingly, not all of them are coffee brands.
Of the 117, 42 were coffee-drink brands and 75 were tea-drink brands, and tea brands accounted for 15.6% of the 660 new coffee products.
Coffee, in other words, is breaking out of its old product boundaries.
Not long ago, talking about coffee meant americanos, lattes, cappuccinos and a handful of specialty brews.
Look at today’s menus and the picture is entirely different.
Fruit, tea, floral notes, grains and even local speciality ingredients are finding their way into coffee, which is increasingly bundled with bread, desserts and snacks.
This is not simply brands churning out novelties for their own sake.
The commercial logic behind it answers a very practical question:
how many reasons does a consumer have, in a single day, to buy a coffee?
Mornings call for a lift and something to go with breakfast; midday may call for something to cut through a heavy meal; afternoons call for sweetness and a mood boost; and selling coffee in the evening means confronting worries about caffeine.
A broader product range, then, is essentially a way of widening the hours in which coffee can be sold.
A traditional americano may solve nothing more than “I’m sleepy”.
Fruit coffees, tea-coffee blends, lighter low-burden options and coffee-plus-bakery combinations can answer breakfast, afternoon tea, socialising, after-meal and leisure needs instead.
Once a cup of coffee starts competing for those moments, its rival is no longer just another café.
It is fighting milk tea, bottled drinks, convenience-store breakfasts and even bread and pastries for the same money.
That is what makes the 660 launches genuinely worth watching.
Falling prices change more than a few yuan off the bill
The other change is price.
Coffee used to come with a fairly clear barrier to entry.
At RMB 30 or 40 a cup, you would pause to ask whether it was worth it; one cup a day meant close to RMB 1,000 a month.
But once prices fall into the RMB 9.9, 12.9 or 15 range — or lower — the logic of buying changes.
Data from Hongcan show that average spend per visit at coffee outlets declined steadily from 2024 to 2026, settling at around RMB 25 in the first half of 2026. Among new products, the RMB 10-15 price band accounted for 9.9% and those below RMB 10 for 11.7%.
The biggest effect of cheaper coffee is not simply “saving ten yuan”.
It is lowering the mental effort each purchase demands.
It is much like bottled water or a morning soy milk.
At over RMB 30, you might ask, “Shall I have a coffee today?”
At a dozen yuan or so, you are more likely to ask, “Americano or latte today?”
The first question decides whether to buy at all; the second only decides which one.
Cross that threshold and frequency can change.
Which is why the most visible trend in China’s coffee market in recent years has not been turning more people into “coffee lovers”, but getting more and more of them into a regular buying habit.
Yet there is a very important commercial paradox here:
the more coffee resembles a daily necessity, the more cups may be sold, but the harder it becomes to earn a high margin on any single one.
Low prices buy frequency, but they also squeeze per-cup gross profit.
So whether a coffee shop makes money can no longer be judged on volume alone.
After 284,000 outlets, competition shifts from “is there one?” to “is it close enough?”
By June 2026, China had 284,000 coffee outlets, up 20.1% year on year, with a chain-store penetration rate of 47.3%.
The report also shows coffee outlets in more than 90% of Chinese cities, with stores in third-tier and smaller cities still growing quickly.
That signals an important shift.
In a growing number of cities, the question facing consumers is no longer “is there coffee nearby?” but rather:
which cup of coffee is closest to me?
For an everyday purchase, “close” matters a great deal.
People may happily drive half an hour for a meal at a speciality restaurant, but few will go far out of their way every day for a coffee costing a dozen yuan.
So as coffee becomes a high-frequency purchase, one of the core resources the industry fights over expands from prime units in big malls to any location close enough to the customer.
Neighbourhoods, office buildings, schools, hospitals, industrial parks, metro entrances, transport hubs and even a few square metres inside a convenience store can all become points of sale.
That explains why coffee outlets are getting smaller.
Grab-and-go counters, kiosk stores, neighbourhood shops, shop-in-shop formats and unattended coffee machines keep appearing.
What customers want is not necessarily a beautifully fitted café where they can sit for two hours.
Often they simply need to grab a cup in two minutes on the way to work.
Those are two businesses with entirely different cost structures.
Why are convenience stores and tea shops starting to sell coffee?
If coffee really is becoming a daily commodity, one consequence is inevitable:
more and more people will sell it.
The report shows that 69% of the top 100 tea-drink brands by store count have already added freshly made coffee to their offer.
Convenience stores are taking another look at coffee too.
Western fast-food chains and bakeries established fairly stable coffee sales models even earlier.
The logic is not complicated.
They already have the customers.
A bakery already has people coming in for bread in the morning; add a coffee machine and a RMB 15 transaction can become RMB 25.
Convenience stores already handle breakfast, commuting and late-night purchases. If freshly ground coffee can be slotted in, the aim is not to make customers come specially for coffee, but:
to add a cup while they are buying a rice ball.
Tea shops work the same way.
The rent is already paid, the staff already on site, and the supply chain, membership scheme and delivery system already in place. If adding coffee opens up new dayparts, the marginal cost of one more cup can be lower than opening a separate independent café.
So what is really happening is not a simple case of “crossing into a new category”.
Coffee is turning from a type of store into a standardised product capability.
You once needed a café to sell coffee.
Going forward, a high-frequency consumption setting may be all a place needs to sell it.
Why more coffee drinkers do not necessarily make cafés more profitable
That also answers an apparently contradictory question:
why, as more people drink coffee, are cafés not necessarily making more money?
Because a bigger market does not mean every store’s profit grows with it.
Suppose a cup falls from RMB 30 to RMB 15, and a customer goes from two cups a week to four.
From the customer’s point of view, coffee has clearly become a high-frequency purchase.
For the store, whether revenue grows depends on several other numbers:
How many cups can it sell in a day?
Are orders spread evenly enough across morning, noon and evening?
How much rent is allocated to each cup?
What is the labour cost?
What do platform delivery and marketing cost?
Does the floor space generate enough revenue?
And what about the cost of beans, milk, fruit and other ingredients?
That is one of the biggest differences between a daily-necessity business and a lifestyle business.
The former tends to depend far more on turnover efficiency.
Once prices fall, a store has to squeeze profit back out through higher order density, lower fixed costs and better utilisation of equipment and staff.
A shop busy for only two hours each morning and largely idle the rest of the day may look healthy in footfall yet still be an inefficient business.
By contrast, a grab-and-go counter of barely a dozen square metres — selling breakfast coffee in the morning, after-meal cups at noon, fruit and tea coffees in the afternoon, plus delivery orders — may generate more sales per square metre.
Once coffee truly enters the mass-consumption stage, the story gets easier to tell and the efficiency harder to deliver.
Coffee is becoming a business of “time”
So what the 660 launches really reveal is not how inventive the coffee industry is.
It is that a cup of coffee is competing for more of the 24 hours in a day.
In the morning it competes with soy milk and breakfast milk.
In the afternoon, with milk tea and sugar-free tea.
In convenience stores, with bottled drinks.
On delivery platforms it even vies with desserts and baked goods for afternoon-tea orders.
Once coffee shifts from “going out specially for it” to “picking one up along the way”, the whole industry’s value chain changes.
Brand still matters, but proximity matters more;
taste still matters, but repeat purchase matters more;
store count still matters, but the single-store model matters more;
new products still matter, but whether they can fill previously idle dayparts may matter more.
Of course, coffee becoming a daily commodity does not mean every brand must take the low-price route.
Specialty coffee, premium spaces and distinctive experiences will keep their own market. Hongcan’s data, after all, only observe sample brands and dedicated coffee outlets; they cannot stand for all coffee consumption.
And low prices are a double-edged sword.
They can widen the customer base and raise how often people drink, but they can also put stores under greater cost pressure. Whether a cup of coffee is a good business still comes back to rent, labour, ingredients, delivery fees and order density.
One thing, though, is becoming ever clearer:
China’s coffee market is moving from “teaching consumers to drink coffee” into a stage of “letting consumers buy coffee whenever they like”.
The two stages look only a few words apart, yet their business models are entirely different.
The first was a contest over who most resembled a good café.
The second is a contest over who can make itself easiest to buy in the morning, at the office, in convenience stores, in neighbourhoods and on delivery platforms.
So looking at the coffee business in future may mean no longer asking only:
How many stores does this brand have?
but asking four more questions as well:
At what price does it sell? How often do customers buy? How many dayparts can it cover in a day? And how much floor space and cost does it take to fulfil those orders?
As those four numbers grow in importance, what is really changing in Chinese coffee is not just taste.
It is that coffee, like breakfast, bottled water and afternoon tea, is becoming an everyday purchase you can make without thinking hard about it.
And once an industry reaches that point, the next round of competition is no longer about who can tell the most elevated story about a cup of coffee.
It is about who can, with greater efficiency, sell that cup into more people’s every day.
Reprint Note & Disclaimer
- This article is reprinted from Chinese media for information and cultural exchange. The views expressed are those of the original author and do not necessarily reflect the position of coffeeyo.com.
- All trademarks, brand names and logos mentioned belong to their respective owners.
- For cooperation, reprint or correction requests, please contact coffeeyo.com.
Reprint Notice & Disclaimer
- This article has been edited and compiled by China Coffee Network. The information and images therein come from public sources and the copyright belongs to the original author. This reprint is intended solely for information sharing within the coffee industry and does not represent the views of this website; all data and opinions are subject to the original article. Our thanks to the original author for creating and sharing it.
- For matters concerning content licensing, attribution, copyright or otherwise, please contact us promptly and we will verify and cooperate in handling them as soon as possible. We also welcome coffee origins, brands and industry media to exchange ideas and contribute articles.
- Contact China Coffee Network: Tel 400-0000-641 (+86-18288016826) | Email 405854472@qq.com | Address: Jinghong, Xishuangbanna, Yunnan Province / Tieling, Liaoning Province
Related Reading
 ‘All-Ice’ Coffee Goes Viral! Will the Next Hit Be Your Personal Favorite?
- Hong Kong’s Dyee Coffee Lands in Qianhai, Building a Specialty Pour-Over Outpost
 Ken Yue Coffee Opens Egg-Tart Pop-Up in Hangzhou: Sweet Craft, Reinvented Classics
 World Cup Enters the Breakfast Slot: Can Coffee-Tea Brands Turn Traffic into Orders?
- ICE Agricultural Futures Mostly Rise at Close; Coffee Futures Up 3.28%
- ‘Sleep Cafés’ Become a New Favorite Among Seoul Office Workers


 Liaoning ICP Security No. 21122402000217